Business
Managing Business Security In-House or With a Specialist Provider

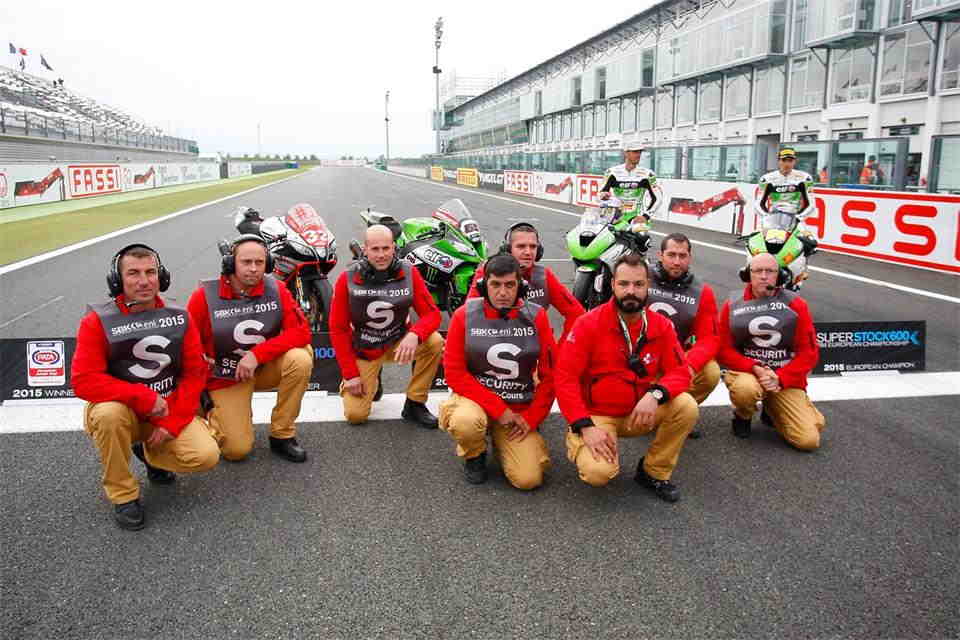
A clear scope matters more than the choice of guard team. The choice between an internal team and a specialist provider works best when it starts with risk and steady workload, not with hourly rates.
Start with risk and workload, not price
Risk assessment comes before staffing decisions. It maps what could go wrong and how likely it is. It covers entry points and high-value areas, along with people flow and past incidents. It also looks at hours when the site is empty or thinly staffed.
A business with night receiving and weekend public access has a very different workload from a business with one office that locks at six and stays shut until morning. The first needs constant cover across shifts and locations. The second may need only periodic checks and a clear escalation path. That difference determines whether an internal team can stay productive or will sit idle between incidents.
Cost comparisons mislead without that picture. An internal hire can look cheap per hour until relief, turnover, supervision, and training are added to the math. A provider quote can look high until night cover and backfill are factored in. Hours alone don’t tell the story, and day rates hide the cost of gaps.
Insider risk belongs in the same review. Staff and contract workers have access and trust, which can be misused by mistake or on purpose. Vetting and consistent oversight lower that risk in both models. No staffing choice fixes weak day-to-day discipline.
Those everyday controls matter more than the hourly rate.
What internal security really demands each week
Running guards in-house means the business is the employer in full. It handles hiring and background checks, along with rosters and pay. It also handles relief when someone calls in sick or takes leave.
Cover is the hard part. A single 24-hour post doesn’t mean three guards. It means four or five once days off, leave, sick time, and turnover are counted. Nights and weekends are harder to fill. If one person quits, the roster breaks fast.
A manager who has to fill a night vacancy at short notice and also deal with reports, access faults, visitor issues, and callouts will feel the strain within weeks. Experience shapes quality more than headcount does. A guard who has worked busy lobbies and industrial gates reads people faster than a new hire with only classroom training. Skills that matter include calm communication and clear report writing.
Supervision can’t stop at 5 p.m. Someone has to check posts at night and review incident notes. Without that layer, standards drift. Cameras and logs help, but they don’t replace a person who walks the site and talks to the team.
In-house can work well when volume is steady and leadership is present. It struggles when sites are spread out or demand spikes without warning.
What a provider changes and what stays with you
A provider takes hiring and shift cover off the internal desk. It hires and vets guards, sets rosters, and arranges relief. The provider holds licenses and insurance for its staff and keeps training records. That shift helps when cover must stretch across nights and weekends at more than one site.
It doesn’t remove accountability from the business. Duty-of-care responsibilities for workers, visitors, contractors, and guests generally remain with the site owner, even when guards wear another badge. If someone is hurt or access fails, questions come back to the business and how it set expectations. A contract that spells out duties, hours, supervision, and reports gives both sides a clear reference when an incident is reviewed several weeks later.
Internal ownership never goes away. Someone inside still has to own the relationship, agreeing on post orders and escalation paths. That person reviews incident reports and checks that patrols happened as agreed. They also connect guards with facilities and IT so small issues don’t grow.
Post orders spell out duties by location and shift, while escalation maps say who is called and in what order. Review meetings track response times and missed tasks.
A provider can ease the load. It can’t replace clear direction from inside.
How to judge providers on capability, not promises
Price tells little about night performance. Capability tells more. Start with proof of scale that matches the task. A provider that staffs several concurrent sites will have relief pools and supervisors. A smaller provider may have deep local knowledge and direct access to senior staff. Both models can work. The fit depends on hours and spread.
Ask for licenses and insurance in writing. Ask how guards are vetted and how long they stay. High turnover breaks site knowledge fast. Retention numbers and supervisor ratios say more than brochures do.
Ask how calls and alarms are handled after hours, including who answers first and how fast a supervisor can attend. Establish what happens if police or emergency services are needed. Clear answers beat vague promises, and they don’t take long to test. Written response targets with time bands and exclusions are more useful than broad claims, since no provider can stop every incident.
A security brand name helps as one signal among others. A provider that has handled complex sites over time has a track record that can be checked. That history doesn’t prove fit for a specific site, and a smaller team can still be the right fit for a single location with stable needs. References and site visits give a clearer view.
During selection, many managers include a known name such as AG Security Group alongside other providers to compare scope and service terms side by side. Keep comparisons like for like. Match hours, duties, supervision, and equipment in each quote.
Guards, patrols and technology as a combined mix
Static guards suit places where presence deters or helps. Front desks and loading docks need a person who can greet people and check access. That presence is steady but it costs more per hour than other layers.
Mobile patrols stretch cover across sites that don’t need a full-time post. One car can check several locations per night, testing doors and resetting alarms. It can also respond to callouts within an agreed window. Patrols don’t sit on site, so gaps remain between visits.
Electronic systems add eyes when staff aren’t there. Cameras, access control, alarms, and intercoms record events and slow intruders. They need power and upkeep, and someone has to watch or review. Remote monitoring can watch feeds in real time and call the site or a patrol when something looks off.
A site that pairs a night patrol with monitored alarms and access logs will have a clearer record of who entered and what response followed than a site that relies on memory alone. Video analytics can flag motion or loitering for a person to review. It works best when tuned to the site’s lighting and traffic. Human review stays central. It also raises privacy questions that need clear signage and retention rules.
Guards handle judgment and direct contact. Patrols and systems provide coverage and records across hours when posts are empty.
Where physical security meets cyber and privacy limits
Physical and cyber risks often overlap. A stolen badge can open a server room, while a weak password can expose camera feeds. Staff use the same doors and networks each day. That link doesn’t mean one team should run both.
Boundaries keep both sides safe. Physical teams handle locks, keys, visitor logs, and patrol response. IT teams handle networks, passwords, system patches, and user access. When duties blur, fixes get missed and blame spreads. A short written division of duties that names who owns cameras, who owns network access, who approves changes, and who reviews logs stops most confusion.
A business that keeps badges and remote access under separate approvals will spot misuse faster than one that lets a single password open doors and systems together. Cameras and access logs collect personal data. Staff and visitors need to know what is recorded and why. Retention and access need clear limits. A clear notice and a simple request process reduce disputes.
Testing needs care and consent. A walk-through of doors and alarms with managers in the room is useful. A simulated intrusion or phishing simulation is useful only with prior written approval, a set scope, a stop rule, and a debrief. Unscoped tests can break trust and breach rules. They can also create safety risks if guards or staff react in real time.
Facilities locks and unlocks while IT watches logs and access. Leaders review what lagged and set the next fix.
Keep a small core inside and review the model each year
Many businesses land on a hybrid. A small internal lead sets policy and runs the provider relationship. The provider staffs posts and patrols and covers nights and leave, with specialist help called for investigations or surge cover. That split keeps control inside while buying depth outside.
Total cost needs a full view. Wages are only part of in-house cost. Add hiring, uniforms, radios, training time, supervision, insurance, and admin. Provider fees need the same full view, including extra callouts, equipment hire, overtime bands, and holiday rates. Side-by-side quotes show true gaps only when hours and duties match.
Good contracts list post duties and patrol frequencies. They list response targets by priority and area, with allowances for distance and traffic. Exclusions cover matters such as those that need police. They state plainly that no provider can prevent every incident. They don’t promise perfect prevention.
A yearly review that compares total spend, response times, missed visits, and feedback from site managers will show if the mix still fits or if hours and posts need to change. Look at incident trends and near misses, along with new sites, new hours, new risks, and new tenants. Look at guard stability and report quality. The right answer shifts as the business shifts.
The model needs to fit the business’s current risk and hours. Start with scope each time and keep ownership inside the business. Test providers on proof, not pitch. Revisit the decision when circumstances change.
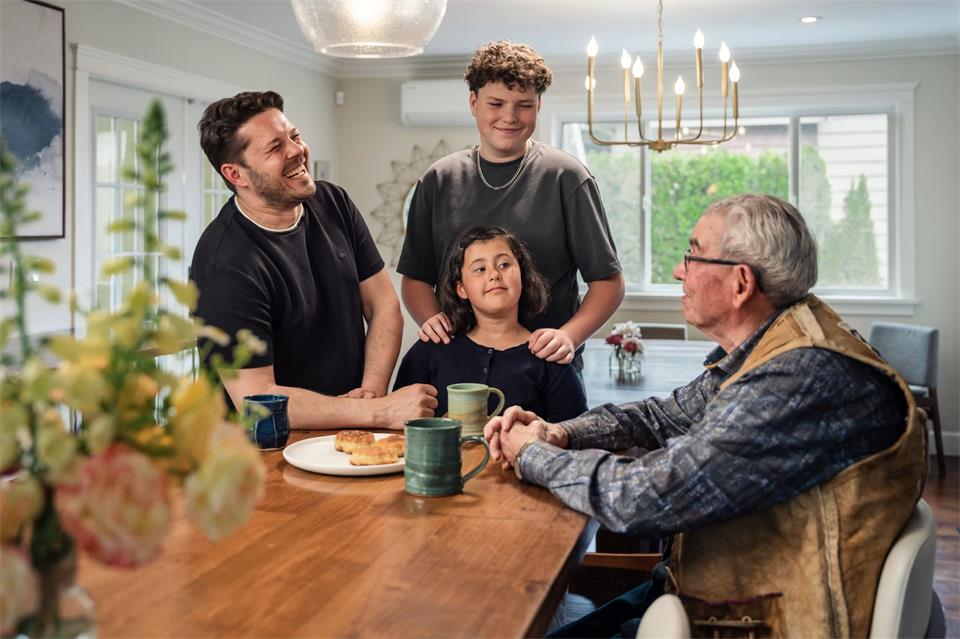
An inherited family home can become the center of a painful disagreement when memories collide with money. While one sibling sees a place filled with childhood memories worth preserving, another may see a valuable asset that needs to be sold. Add repair bills, property taxes, and differing financial priorities, and even close family relationships can come under pressure. Resolving shared inheritance disputes requires more than good intentions; it takes clear communication, financial transparency, and a practical understanding of each co-owner’s legal rights.
Common Sources of Co-Owner Conflict
Conflict often begins because family members have different expectations. One heir may see a childhood home as part of the family’s history. Another may view it as an asset that should be sold quickly. Disagreements can also involve who gets access, who chooses tenants, and how personal belongings are divided. Recognizing the emotional importance of the bond and shared memories between brothers and sisters can help families understand why inherited property decisions sometimes become deeply personal.
Common sibling inheritance problems become harder to resolve when nobody has current information. Order an appraisal, inspect the property, and confirm each person’s ownership share. Then put all proposals in writing. A shared email thread or online folder gives everyone the same records and reduces arguments about what someone previously promised.
Financial Burdens of Shared Property
Ownership expenses continue even when the family hasn’t decided what to do. Property taxes, insurance, utilities, and emergency repairs can create immediate pressure. If one co-owner pays a $4,000 repair bill alone, that person may expect reimbursement later, but the others may dispute whether the work was approved or necessary.
Create a property account and require receipts for every payment. Agree in writing on monthly contributions, spending limits, and reimbursement rules. Guidance about inheriting with siblings also highlights options such as a buyout or sale.
When ownership rights, unpaid expenses, or control of the property are already disputed, consulting a Real Estate Attorney can help owners in North Carolina or South Carolina assess the available legal options.
Partition Actions and Legal Remedies
A partition action asks a court to end shared ownership when the co-owners can’t agree voluntarily. Depending on the property and applicable state law, the court may divide the land, order a sale, or use another process to distribute its value. A house on a standard residential lot usually can’t be physically split, so a sale may be the practical result.
Court action can involve filing fees, appraisals, legal costs, and delays. It may also reduce the family’s control over the timing and sale terms. Before filing, consider a written buyout proposal, mediation, or an agreed market sale. Keep records of repair payments, rental income, and taxes because those figures may affect the final accounting between owners.
Create a Clear Resolution Roadmap
Set a firm schedule so the property doesn’t remain in limbo. Start with an appraisal and title review, then give each owner a deadline to choose among keeping, selling, or buying out the others. If someone wants a buyout, require proof of financing within a defined period, such as 30 or 45 days.
The written plan should also identify who maintains the property, how offers will be reviewed, and what happens if a deadline passes. Include a method for resolving smaller disputes, such as mediation with a neutral professional.
Family members don’t need to agree about the home’s emotional meaning. They do need accurate numbers, written deadlines, and a workable exit option. A signed roadmap can keep the next missed tax payment or repair bill from becoming the event that sends everyone to court.
Royalty checks can look dependable one quarter and shrink sharply the next. Production rates, commodity prices, operator deductions, and ownership details all affect what reaches your bank account. Selling may provide useful liquidity, but keeping the interest could preserve years of future income.
The decision deserves more than a quick comparison between the latest check and a purchase offer. Review production history, recurring administrative costs, valuation assumptions, and the potential use of sale proceeds before choosing a direction.
Analyzing Production Decline in Aging Basins
Start with monthly production records for each well tied to your royalty interest. Most wells decline over time, although new drilling, maintenance work, or improved market conditions can temporarily lift payments. Technical professionals use decline-curve methods to estimate future output, and reviewing published technical papers can help you understand the analytical work behind those forecasts.
Look beyond the last six months. A three-to-five-year record may reveal a clearer trend and expose unusual spikes. For example, a royalty paying $800 per month today may be less attractive if production has fallen 15% annually. Ask whether nearby development is likely, but don’t assign value to drilling that hasn’t been approved or funded.
The True Expense of Annual Compliance
Royalty ownership creates work even when payments are modest. You may need to review tax documents, track deductions, update estate records, and resolve payment suspensions caused by title questions. Professional fees can consume a meaningful share of a small annual royalty, especially when interests are spread across several counties or operators.
Payment calculations also deserve attention. A congressional report concerning royalty payment reductions illustrates why timing and valuation practices can affect owner revenue. If ongoing administration has become burdensome, requesting an offer from Harbor Energy LLC can give you a concrete figure to compare with expected net income. Include accounting, legal, and recordkeeping costs in that comparison.
Getting a Transparent Fair-Market Valuation
A serious valuation should explain the assumptions behind the number. Ask how the buyer treated recent production, expected decline, commodity pricing, operator deductions, and undeveloped acreage. Confirm exactly which interests the offer covers because a broad legal description could include more acreage or rights than you intended to sell.
Compare at least two written offers using the same ownership documents. A $60,000 offer with no owner-paid closing expenses may produce more cash than a higher headline amount reduced by fees or title adjustments. Review the proposed deed and purchase agreement with a qualified attorney who represents you. Also ask what happens if title verification finds that your decimal interest differs from the amount shown on recent statements.
Calculating the Opportunity Cost of Waiting
Keeping royalties has a cost that doesn’t appear on an operator statement. Money tied to an unpredictable income stream can’t be used to reduce expensive debt, build a diversified portfolio, or cover a planned expense. Compare the expected after-tax proceeds from a sale with a conservative estimate of future after-tax royalties. When weighing how to use potential sale proceeds, consider investment options that can help build long-term financial security.
Suppose an interest generates $9,000 per year but declines by 12% annually. Holding it for five years may produce far less than simply multiplying $9,000 by five. Still, future drilling could change the result. Run several cases using low, middle, and high production assumptions. Then compare those outcomes with a specific use for the cash, including the likely return and the risks involved.
A sale makes the most sense when the certainty and practical value of cash outweigh your realistic estimate of future net payments. Before signing, verify the ownership covered, calculate the tax impact with an adviser, and keep copies of every statement used to support the valuation.
Law
Unlocking Real Estate Inheritance: Understanding How Long Probate Takes in NSW Before Selling a Home
An inherited home can be one of an estate’s most valuable assets, but selling it in New South Wales involves more than calling an agent and setting a price. The executor or administrator needs legal authority to deal with the property, beneficiaries may need time to agree on practical matters, and the sale itself has to fit within the wider administration of the estate.
Probate timelines vary, so families should avoid making firm promises about settlement dates too early. A clearer picture of the process can help you plan maintenance, manage expenses and decide when the property is ready for market.
What probate means for an inherited home
Probate is the Supreme Court’s formal recognition of a valid will and the executor named in it. Once the Court issues a grant of probate, the executor has evidence of their authority to collect assets, pay estate liabilities and distribute the remaining estate according to the will.
If a person dies without a valid will, the process is different. An eligible person generally applies for letters of administration and the estate is distributed under intestacy rules. Although people often use “probate” as a broad label for estate administration, the type of grant affects who can act and what documents will be required.
For real estate, this authority matters because a beneficiary doesn’t automatically become the registered owner on the date of death. The title records and estate documents must be dealt with correctly. An executor may eventually transfer the home to a beneficiary or sell it and distribute the net proceeds, depending on the will, the estate’s debts and the beneficiaries’ circumstances.
The post-grant administration process may include collecting money, selling assets, paying debts and preparing an account for beneficiaries. That means the property sale is usually one part of a larger job, not a separate transaction.
How long the process may take
There’s no single probate timetable that applies to every NSW estate. Straightforward applications can move relatively quickly once the required notice period has passed and all documents are ready. Delays may arise if the original will is missing, the will contains an error, an executor has died or renounced the role, or the Court asks for more evidence.
Court processing is only one part of the timeline. Before applying, the executor usually needs the death certificate, original will, and a reliable list of estate assets and liabilities. Locating bank accounts, checking the property title, and confirming outstanding loans can take several weeks, especially when records are incomplete.
A practical guide to how long probate takes can help an executor understand the likely stages and consider when legal advice may be useful. Broader discussions of common probate delays also highlight factors such as family disputes, complex assets and paperwork problems, though overseas procedures and time estimates don’t replace NSW-specific advice.
Consider an estate with one home, one bank account and a clear will. Its application may be simpler than an estate involving a business, several properties and unclear beneficiary details. Executors should treat any quoted timeframe as an estimate and keep written records of requests, documents received and outstanding tasks.
Can you prepare a sale before probate is granted?
Preparatory work can often begin before the grant arrives, but the executor should confirm the legal position before signing a contract or committing the estate to a settlement date. The exact options depend on the title, the wording of the will and how the proposed contract will deal with the pending grant.
Useful early tasks include obtaining market appraisals, checking insurance, arranging urgent repairs and gathering council or strata records. Executors can also speak with a conveyancer or solicitor about the contract documents that will be needed. This preparation may reduce idle time once authority to proceed is clear.
Marketing decisions deserve care. An agent may be able to photograph the property and discuss a campaign before probate, but buyers need accurate information about the seller’s capacity and any conditions affecting settlement. Accepting an offer that requires a quick settlement can create trouble if the grant has not arrived or title requirements remain unresolved.
General guides to the inherited home sale timeline show that preparation, marketing and closing each take time. Since that resource discusses a different legal system, use it only for broad sale-planning ideas. NSW legal advice should guide the contract, disclosure requirements and authority to sell.
Avoid distributing sale proceeds as soon as they reach the estate account. The executor may first need to pay liabilities, allow for tax and administration costs and address any potential claims against the estate.
What can slow down the sale
A probate grant doesn’t guarantee that the home will be ready to list immediately. Physical, financial and family issues can all add time after the legal authority is in place.
The condition of the property is a common factor. A vacant home may need cleaning, garden work, safety repairs or removal of personal belongings. If somebody still lives there, the executor may need advice before discussing access or moving arrangements. Informal assumptions about who may stay in the home can quickly create conflict.
Ownership details can also complicate matters. A property held solely by the deceased may be treated differently from one held jointly with another person. Mortgages, caveats and other title interests need to be identified early. In a strata property, unpaid levies or missing records can delay contract preparation.
Beneficiary disagreement creates another practical hurdle. One person may want a quick sale, while another hopes to keep the home or wait for a higher price. The executor must follow the will and perform their legal duties, so a family vote doesn’t always decide the issue. Independent valuations and written advice can keep the discussion tied to evidence.
Tax should be reviewed before a price is accepted. Capital gains tax treatment may depend on matters such as when the deceased acquired the property, how it was used and when the estate sells it. An accountant can assess the estate’s circumstances and estimate the amount that should remain available for tax and other costs.
A practical plan for executors
Start by securing the property. Check that insurance remains suitable after the owner’s death, particularly if the home is vacant. Collect keys, redirect essential correspondence and keep records of any estate money spent on rates, utilities, insurance or maintenance. Don’t pay estate costs from a personal account without documenting the payment.
Next, build a working file for the property. Include the title search, loan statements, council notices, strata information, repair invoices and at least one market appraisal. If beneficiaries remove furniture or personal items, record what was taken and under what authority. Clear records reduce confusion when the executor prepares estate accounts.
Before listing the home, confirm four points:
- The person signing the agency agreement and sale contract has proper authority
- The proposed settlement date is realistic
- The contract contains any terms required because probate is pending
- The estate has funds available for ongoing costs until settlement
Ask the selling agent to explain the suggested price range, campaign length and likely buyer profile. A written appraisal gives the executor something concrete to consider and share with beneficiaries. For an unusual property or a disputed estate, an independent valuation may provide stronger evidence of market value.
Once a buyer is found, keep beneficiaries updated without promising a distribution date. Settlement proceeds may need to remain in the estate while debts, expenses and tax matters are finalized. A short written update explaining the contract price, settlement date and remaining administration tasks can prevent repeated questions.
The safest starting point is a property file that shows the title position, current expenses and the status of the probate application. Those three details will tell your solicitor, accountant and agent what can happen now and what must wait.

When Inherited Real Estate Causes Family Friction

Smart Estate Planning Includes End of Life Logistics

How Winter Property Maintenance Helps Reduce Slip-and-Fall Risks

Managing Business Security In-House or With a Specialist Provider

Is It Time to Cash Out Your Unpredictable Royalties?

125 Inspirational Car Quotes and Captions to Celebrate Your New Car

188 Deep Hurt Quotes with Images

148 Romantic Love Quotes for Her from the Heart

164 Relationship Goals Quotes for New Couples Expecting a Long Lasting Relationship

185 Cute Boyfriend Quotes for the Guy You Love
-
 Quotes6 years ago
125 Inspirational Car Quotes and Captions to Celebrate Your New Car
-
Growth6 years ago
188 Deep Hurt Quotes with Images
-
Quotes6 years ago
148 Romantic Love Quotes for Her from the Heart
-
Quotes5 years ago
164 Relationship Goals Quotes for New Couples Expecting a Long Lasting Relationship
-
Quotes6 years ago
185 Cute Boyfriend Quotes for the Guy You Love
-
Quotes6 years ago
141 Best Heart Touching Quotes about Love, Life, and Friendship
-
Quotes5 years ago
134 Time Flies Quotes for the Unforgettable Moments
-
Quotes6 years ago
122 Inspirational Kite Quotes That’ll Make You Wanna Fly Right Now