Business
Exit Plans for Your Dumpster Rental Business

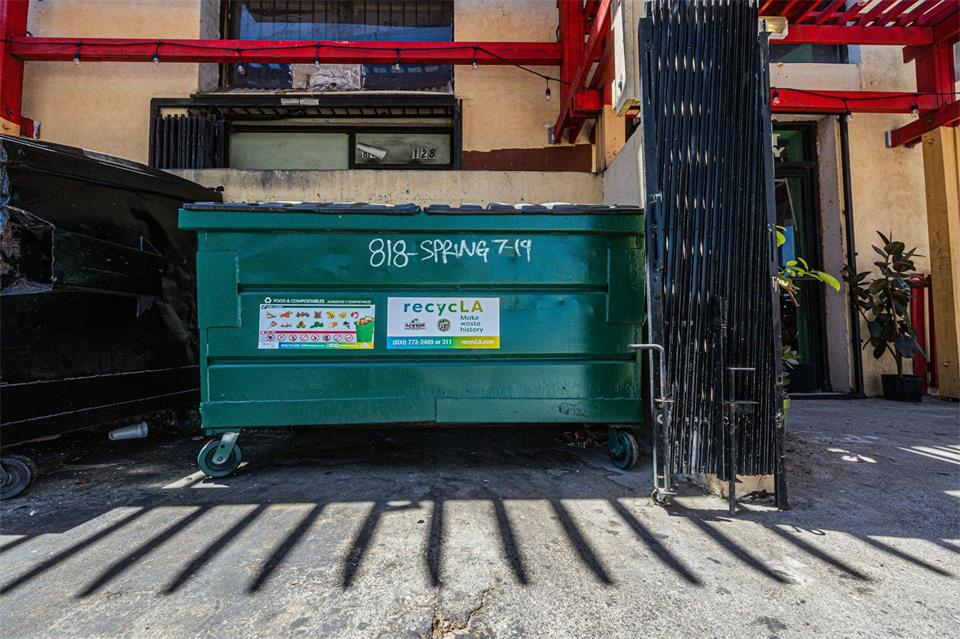
Let’s be honest, no one starts a business with the idea of selling. But for some people, this is the natural end point. Whether you lose the passion for what you have built, you need another challenge, or other life reasons force your hand.
And this is true for many business owners, but in sectors such as waste management — specifically dumpster rentals — where the market isn’t just growing, it’s thriving with a predicted CAGR of 4.7% between 2025 and 2035.
If you’re thinking of selling to make the most of the growing market and get the best price possible, you need to create your exit plan now, even if you don’t plan on letting go immediately. Having the right blocks in place means you can move forward and strike when the opportunity arises without scrambling behind the scenes.
With this in mind, let’s take a look at how you can do just that.
Know What Your Business Is Worth
Before you do anything, you need to know what your business is worth right now. Sure, you think you might know, but generally these figures are overoptimistic or entirely undervalued.
There are multiple factors that can influence your business valuation, including but not limited to:
- Recurring contracts
- Route efficiency
- Profit margins
- Equipment condition and age
- Customer concentration
- Documented systems
- Debt
- Local market competition
It makes sense that you’re not guessing at figures here — that you know exactly what you’re sitting on, so you have a more accurate ballpark figure.
A good starting point is using a Dumpster Rental Business Valuation Calculator to look at your earnings, assets, and trends together as one, instead of guessing. Once you see where you are now, you can make appropriate changes and decisions that either boost or retain the value of the company.
The thing is, if you’re planning an exit strategy, you need to know where you’re working from, and this is the ideal starting point.
Clean Up Financials
Even if you’re not serious about selling and you’re putting together your exit plan for “just in case anything goes wrong,” the truth is that messy financials ruin companies faster than anything else, and businesses that don’t have the books in order are worth less automatically.
Buyers, lenders, and partners don’t want to guess at what they’re getting into. They want accurate numbers. They want clarity. And to deliver this, and even run a more successful business, this means:
- Consistent bookkeeping
- Clear separation of personal and business expenses
- Tax returns that line up with reported earnings
- Accurate depreciation schedules for trucks and dumpsters
- Real-world profit, not just revenue
If your books are inaccurate, not up to date, or simply not documented completely, it’s never too late to fix them — and if you’re in the habit of doing this now, before you plan to sell, it will make life so much easier once the time rolls around.
Document the Business: It Needs to Run Without You
Here’s the thing: if your business can’t run without you knowing and doing everything, it’s not a suitable business — it’s just a huge workload. It’s a demanding job, not a transferable company. And no one wants to walk into that kind of mess.
Exit planning means reducing the company’s need for you to explicitly handle everything alone. And this starts with documenting the key parts of your operations.
Think of it this way: if you left for a month, what would happen? Would the company function — or freeze?
Your systems need to live on paper, and once you realize this, everything becomes stronger.
You need to document things like:
- Daily dispatch procedures
- Billing workflows
- Customer onboarding
- Maintenance schedules
- Pricing structures
- Vendor relationships
- Licensing and compliance steps
Strengthen Recurring & Contract-Based Revenue
You know that dumpster rental businesses only work because of repeat customers — and while one-off rentals are great, it’s those ongoing regular contracts that make the company profitable, especially in the context of exit planning.
This is how you build a business: you focus on people returning and creating ongoing partnerships over those one-off jobs that come and go.
The aim here is to build a business that values existing relationships, and this means you need to focus on ways to do this. Here are some ideas:
- Roll-off contracts with builders
- Recurring service with commercial clients
- Municipal or institutional work
- Multi-property agreements
These are the types of relationships that show stability and predictability — and that stability supports stronger valuations.
From here, you need to ask yourself some questions to decide you’re on the right track: Where is revenue predictable? Where is it fragile? Where do you rely too heavily on one client?
Remember: building revenue takes time — so focusing on this earlier means you have the blocks for your exit plan in place years before it is even something you’re seriously considering.
Focus on Compliance, Safety, and Environmental Issues
Anyone in the waste business knows that permits, paperwork, and compliance aren’t optional — they’re part of the value.
You need to ensure you’re on top of all aspects of compliance applicable to your company — be it DOT compliance, driver training and education, safety logs, insurance at appropriate levels, and keeping landfill and transfer station relationships stable.
You need to be on the lookout constantly for red flags so you can eliminate those, because if you don’t find them or you don’t rectify them, these become leverage for buyers in negotiations and will reduce price regardless of valuation.
Successful exit planning means you’re making decisions with the final sale in mind. Fewer risks, more interest, and the higher the valuation. Even if you never sell, run your company like you are and aim for maximum value.
Build a Timeline
You need a rough timeline for your exit strategy, yes, again, even if you’re not selling. A timeline focuses the company and forces intentional decisions. You can think in terms of 3–5 years, for example, 5–10, or even “after the next growth phase.”
Each timeline changes how you prepare and what decisions you make, and it’s important you review these regularly, especially as each timeline comes to its natural end, so you can keep building, moving forward, and align the right decisions.
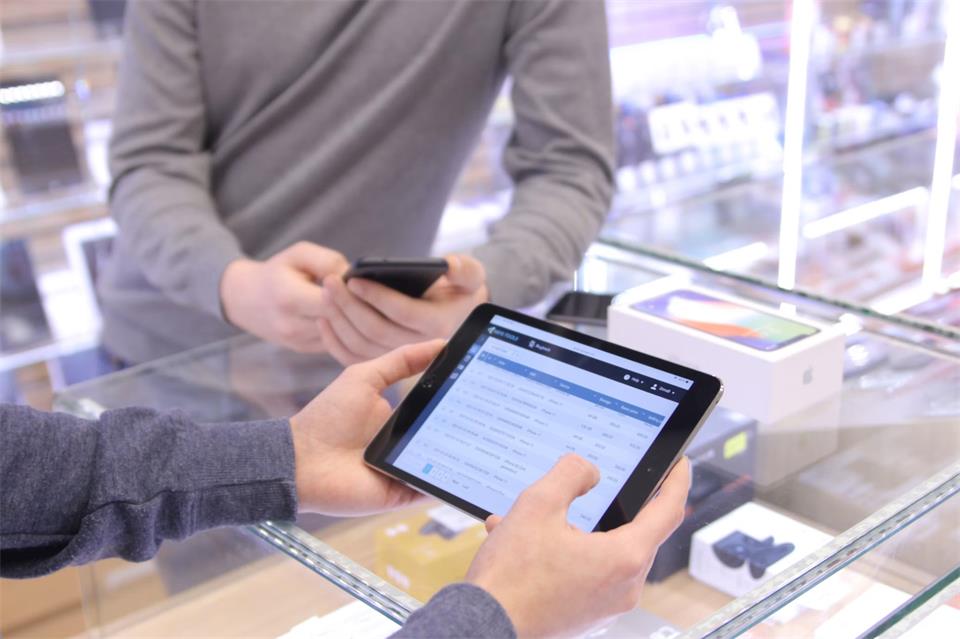
Inventory problems often show up as crowded shelves, delayed orders or cash tied up in products that aren’t selling. For a small business, even modest stock errors can strain the budget and frustrate customers. A practical inventory management system gives you a clear picture of what you have, what’s moving and what needs attention. Consistent records and a few well-chosen routines can also help produce meaningful results.
Start with accurate inventory records
Create one reliable inventory list that includes each product’s name, stock-keeping unit, quantity, cost, selling price and storage location. Record incoming and outgoing items in the same system so employees aren’t working from competing spreadsheets or handwritten notes.
Schedule regular physical counts to check those records. A small retailer might count high-value products every Friday and complete a full count once per quarter. If the system shows 30 units but the shelf holds 24, investigate recent sales, returns and damaged goods. Square’s small business inventory guide offers a useful overview of stock tracking methods and common inventory terms.
Make products easier to identify
Clear product identification reduces picking mistakes and speeds up stock counts. Assign every item and variation a unique SKU, including differences in size, color or package quantity. Place that code on the product, storage bin and inventory record.
Labels should remain readable throughout storage and handling. Businesses packaging goods exposed to moisture or oil may find white roll labels printing useful for creating durable custom labels with permanent adhesive. Include essential details such as the SKU, product name and batch number. A consistent format helps employees identify stock quickly without opening boxes or relying on memory.
Set reorder points that reflect real demand
A reorder point tells you when to purchase more stock. Calculate it using average daily sales, supplier lead time and a reasonable amount of safety stock. If you sell five units per day and replenishment takes eight days, you’ll need at least 40 units to cover normal demand during that period.
Safety stock protects against small delays or sudden sales increases, but too much of it locks up cash. Review reorder points after seasonal peaks, supplier changes and promotions. For growing companies, this inventory planning guidance explains how demand forecasting and stock visibility support expansion without uncontrolled purchasing.
Pay attention to slow-moving stock
Review sales by SKU each month and flag products that haven’t sold within a set period, such as 60 or 90 days. The right threshold depends on the business. A seasonal decor shop will use a different timeline from a store selling everyday household supplies.
Once you identify slow stock, decide why it stalled. The price may be too high, the item may be hard to find online or demand may have changed. Options include creating bundles, moving products to a more visible display or reducing future order quantities. The broader aim is to release cash for dependable sellers, an issue also covered in these ways to cut inventory costs.
Build a routine your team can follow
Inventory management works best when each task has a clear owner and schedule. Decide who receives deliveries, updates quantities, processes returns and approves purchase orders. Write down the process in plain language so a new employee can follow it without guessing.
Keep the routine manageable. Daily updates might take 10 minutes, while a weekly review could cover low-stock alerts, sales patterns and unresolved discrepancies. Each month, check a small set of useful figures, including stock turnover, products out of stock and the value of aging inventory.
The most revealing place to begin is often a shelf count. Compare one high-volume product against its recorded quantity, trace any difference and use what you learn to tighten the process across the rest of your inventory.
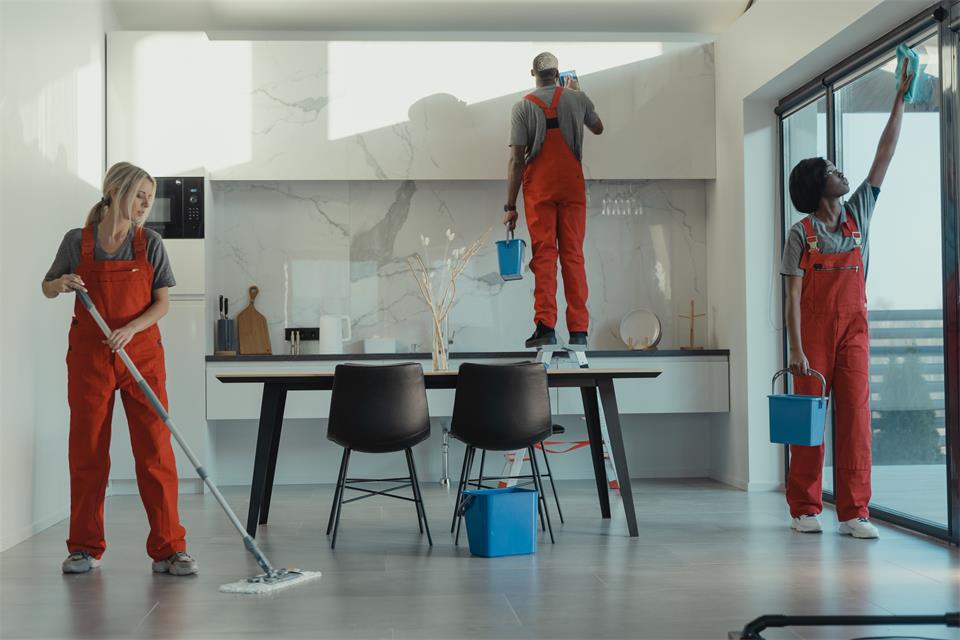
Most cleaning contracts fail quietly. The work continues and the invoices keep arriving, but the decline only surfaces later as a tenant complaint or a dispute about what was ever agreed. For Perth property managers, that decline usually traces back to a small set of avoidable mistakes, and most of them begin at the contract stage, well before anyone notices a dirty lobby.
Hiring on price and skipping the paperwork
The lowest quote usually has a reason behind it, and that reason is often a thinner scope of work rather than a better price. A quote that looks cheap can quietly assume fewer visits per week, a shorter task list, or a rotating cast of casual staff. Comparing quotes line by line against the same written scope is the only useful comparison.
Ask each contractor to spell out the tasks included at each visit, the frequency of periodic work such as carpet cleaning and window washing, and the staffing arrangements behind the roster. A named regular cleaner answers questions that an anonymous crew cannot.
A named on-site supervisor matters for the same reason, giving the manager one person who knows the building and can be reached when something is missed. Ask for the quote to confirm who that supervisor is, how often they inspect the work, and which contact handles day-to-day communication. The answers will separate the quotes faster than the totals at the bottom of the page.
Working without a written scope of works
A cleaning specification, sometimes called a scope of works, is the document that defines what gets cleaned, how often each task happens, which areas are covered and what standard counts as done. Without one, the word clean becomes a matter of opinion, and every disagreement turns into an argument nobody can settle because there’s nothing to point at.
The practical damage shows up in mismatched frequencies: bathrooms serviced on a schedule written for a quieter building, lift lobbies polished daily while end-of-trip facilities wait a week. A written scope also gives both sides the benchmark that any later inspection will be measured against, and it protects honest contractors who would rather price against a clear document than guess. Managers who inherit a contract with no scope should treat drafting one as the first job, because every other fix depends on it.
Buying labor hours when the building needs a managed service
A large commercial asset needs documented processes, scheduled audits, digital reporting and support that answers at night, because the building itself operates on that kind of schedule. Integrated facility management, where the contractor takes on compliance reporting and coordination across multiple sites, sits at the far end of this spectrum and suits larger portfolios. The gap between a cleaner and a cleaning partner is that one supplies hours and the other supplies outcomes that can be verified.
When preparing questions about scope and communication, a reader can consult a website such as purecleanperth.com.au as a starting point for drafting requirements. The mistake is pricing the two models as if they were interchangeable, because the difference only becomes visible when something goes wrong.
Never auditing what was promised
Cleaning quality rarely collapses; it erodes, and erosion is hard to see from a desk. The first signal is usually a tenant complaint, which means the manager learns about the problem after the tenant has already formed a view of the building. Key performance indicators exist to catch the decline earlier: scheduled tasks against completed ones, response times on reported issues, inspection scores and complaint volumes.
Digital site logs give the manager a record that can be checked without chasing anyone. A monthly or quarterly audit rhythm, written into the contract, turns cleaning from a matter of trust into a matter of record. Without that record, the manager is funding a service they cannot verify, and the building’s occupants become the inspection team.
Underestimating the building itself
A multi-level commercial building is an operational environment, and the contract has to account for its logistics before anyone picks up a mop. After-hours access needs to be coordinated with security and alarm systems, which means agreeing on who holds keys and codes, which windows the crew can work in, and what happens when an alarm goes off at the wrong moment. Shared areas such as lift lobbies, stairwells and car parks need a named owner on the cleaning schedule, because spaces that belong to everyone tend to be cleaned by no one.
Storage matters too: a building of this size needs a designated place for equipment and supplies, agreed with building management rather than improvised floor by floor. Tenant needs change as tenancies turn over, so the contract should include a simple channel for passing requests and complaints between tenants, the property manager and the cleaning crew. At this scale, cleaning is coordination as much as labor, and the contract should reflect that.
Each of these mistakes is cheap to fix at the contract stage and expensive to fix after an incident. Pull the current agreement, check it against the points above, and the gaps will usually show themselves within a few pages.
An inherited family home can become the center of a painful disagreement when memories collide with money. While one sibling sees a place filled with childhood memories worth preserving, another may see a valuable asset that needs to be sold. Add repair bills, property taxes, and differing financial priorities, and even close family relationships can come under pressure. Resolving shared inheritance disputes requires more than good intentions; it takes clear communication, financial transparency, and a practical understanding of each co-owner’s legal rights.
Common Sources of Co-Owner Conflict
Conflict often begins because family members have different expectations. One heir may see a childhood home as part of the family’s history. Another may view it as an asset that should be sold quickly. Disagreements can also involve who gets access, who chooses tenants, and how personal belongings are divided. Recognizing the emotional importance of the bond and shared memories between brothers and sisters can help families understand why inherited property decisions sometimes become deeply personal.
Common sibling inheritance problems become harder to resolve when nobody has current information. Order an appraisal, inspect the property, and confirm each person’s ownership share. Then put all proposals in writing. A shared email thread or online folder gives everyone the same records and reduces arguments about what someone previously promised.
Financial Burdens of Shared Property
Ownership expenses continue even when the family hasn’t decided what to do. Property taxes, insurance, utilities, and emergency repairs can create immediate pressure. If one co-owner pays a $4,000 repair bill alone, that person may expect reimbursement later, but the others may dispute whether the work was approved or necessary.
Create a property account and require receipts for every payment. Agree in writing on monthly contributions, spending limits, and reimbursement rules. Guidance about inheriting with siblings also highlights options such as a buyout or sale.
When ownership rights, unpaid expenses, or control of the property are already disputed, consulting a Real Estate Attorney can help owners in North Carolina or South Carolina assess the available legal options.
Partition Actions and Legal Remedies
A partition action asks a court to end shared ownership when the co-owners can’t agree voluntarily. Depending on the property and applicable state law, the court may divide the land, order a sale, or use another process to distribute its value. A house on a standard residential lot usually can’t be physically split, so a sale may be the practical result.
Court action can involve filing fees, appraisals, legal costs, and delays. It may also reduce the family’s control over the timing and sale terms. Before filing, consider a written buyout proposal, mediation, or an agreed market sale. Keep records of repair payments, rental income, and taxes because those figures may affect the final accounting between owners.
Create a Clear Resolution Roadmap
Set a firm schedule so the property doesn’t remain in limbo. Start with an appraisal and title review, then give each owner a deadline to choose among keeping, selling, or buying out the others. If someone wants a buyout, require proof of financing within a defined period, such as 30 or 45 days.
The written plan should also identify who maintains the property, how offers will be reviewed, and what happens if a deadline passes. Include a method for resolving smaller disputes, such as mediation with a neutral professional.
Family members don’t need to agree about the home’s emotional meaning. They do need accurate numbers, written deadlines, and a workable exit option. A signed roadmap can keep the next missed tax payment or repair bill from becoming the event that sends everyone to court.

How Small Businesses Can Improve Inventory Management

How to Choose Timeless Jewelry That Reflects Your Personal Style

The Unexpected Challenges of Moving Somewhere New

Common Commercial Cleaning Mistakes Perth Property Managers Can Avoid

When Inherited Real Estate Causes Family Friction

125 Inspirational Car Quotes and Captions to Celebrate Your New Car

188 Deep Hurt Quotes with Images

148 Romantic Love Quotes for Her from the Heart

164 Relationship Goals Quotes for New Couples Expecting a Long Lasting Relationship

185 Cute Boyfriend Quotes for the Guy You Love
-
 Quotes6 years ago
125 Inspirational Car Quotes and Captions to Celebrate Your New Car
-
Growth6 years ago
188 Deep Hurt Quotes with Images
-
Quotes6 years ago
148 Romantic Love Quotes for Her from the Heart
-
Quotes5 years ago
164 Relationship Goals Quotes for New Couples Expecting a Long Lasting Relationship
-
Quotes6 years ago
185 Cute Boyfriend Quotes for the Guy You Love
-
Quotes6 years ago
141 Best Heart Touching Quotes about Love, Life, and Friendship
-
Quotes5 years ago
134 Time Flies Quotes for the Unforgettable Moments
-
Quotes6 years ago
122 Inspirational Kite Quotes That’ll Make You Wanna Fly Right Now